
Rental income in the European Union with Russian tax residency: what the suspended agreement means

Rental income from an apartment in the European Union is taxed where the property is located — in the country where the apartment stands — and at the same time declared in the owner's country of tax residence. For a Russian tax resident, these two obligations used to be reconciled by a double taxation avoidance agreement; since 2023 its main provisions have been suspended. Below — where and how the tax is paid, what exactly the suspension changed and which documents prove payment.
In brief. Tax on renting out an apartment in Romania is paid in Romania, where the property is located — Romania's Tax Code, Law 227/2015, administered by ANAF. A Russian tax resident declares the same income in Russia under the Tax Code of the Russian Federation. The Convention between Russia and Romania of September 27, 1993 is not fully in force: Articles 5–23 and 25 have been suspended since August 8, 2023 by Decree No. 585 and Law No. 598-FZ. A calculation that relies on the suspended provisions is invalid and is redone under the national codes of both countries; rates are not given in this article.
Where is the tax on renting out an apartment in Romania paid?
In Romania, where the property is located. Romania's Tax Code — Law 227/2015, in force since January 1, 2016 — taxes a non-resident's income from real estate located in Romania in Romania, regardless of where the owner lives. The tax is administered by ANAF.
ANAF is the National Agency for Fiscal Administration, Romania's tax authority. A foreigner renting out an apartment registers the income and pays the tax through it — personally or through a management company under a contract.
The second place is the owner's country of tax residence. For a Russian resident, that is Russia: the same income is declared there under the Tax Code of the Russian Federation. How the two obligations relate to each other used to be governed by the agreement between the countries; where it stands now is covered in the next section.
What does the suspension of the double taxation avoidance agreement mean?
The main articles are suspended, not the agreement as a whole. The Convention between the Government of the Russian Federation and the Government of Romania for the avoidance of double taxation was signed on September 27, 1993; by Decree of the President of the Russian Federation No. 585 of August 8, 2023 and Federal Law No. 598-FZ of December 19, 2023, Articles 5–23 and 25 have been suspended since August 8, 2023.
In practical terms: the rules allocating the right to tax and the relief provisions of the suspended articles do not apply to income received from that date. Both countries calculate the tax under their own national codes. The status of the agreement on the Romanian side is checked with ANAF as of the relevant date.
We close off one conclusion right away: the suspension does not cancel the obligation to pay in either country — it cancels the reliance on relief. No rates for either country are given here: they are calculated for the specific situation and they change.
Who is a tax resident and how is it determined?
A tax resident is a person who, under a country's rules, must pay tax there on all of their income, regardless of the country where it is earned. Romania determines residence under Article 7 of the Tax Code: domicile in Romania, the center of vital interests, or a stay of more than 183 days in any 12 consecutive months.
Russia determines residence under Article 207 of the Tax Code of the Russian Federation: at least 183 days within 12 consecutive months. An owner who lives in Russia and rents out an apartment in Romania remains a Russian tax resident, and in Romania pays as a non-resident — where the property is located.
Residence is confirmed by a document: in Romania, by a tax residence certificate from ANAF; in Russia, on request to the Federal Tax Service. Without a document, the status is determined by the actual days of presence, and a dispute over days is the most common cause of double counting.
How is income structured through a Romanian company?
Through an SRL that owns or manages the apartment and signs lease agreements in its own name. An SRL is a limited liability company under Romanian law; registration takes about a month and costs €1,300 — on confirmed terms as of September 1, 2026.
The company pays tax in Romania under its own regime. The micro-enterprise regime gives way to the standard regime once a revenue threshold is crossed, not because an apartment is bought. Income reaches the owner as dividends: the tax is withheld at source in Romania, and the dividend itself is declared in the country of residence. Rates are not given.
As an individual.
Who pays the tax in Romania — the owner as a non-resident, through ANAF.
What is declared in Russia — the rental income.
Payment documents — the single tax return, the payment, an ANAF certificate.
When it fits — one apartment, simple reporting.
Through a Romanian company.
Who pays the tax in Romania — the company under its own regime, then the tax on dividends.
What is declared in Russia — dividends from the company.
Payment documents — the company's returns, payments, the dividend resolution, an ANAF certificate.
When it fits — several properties, management through a management company.
The choice between the two formats is made during the assessment, based on the number of properties, the holding period and
how the owner intends to receive the income. A company does not give any status in the European Union and does not affect the tax in the country of residence.
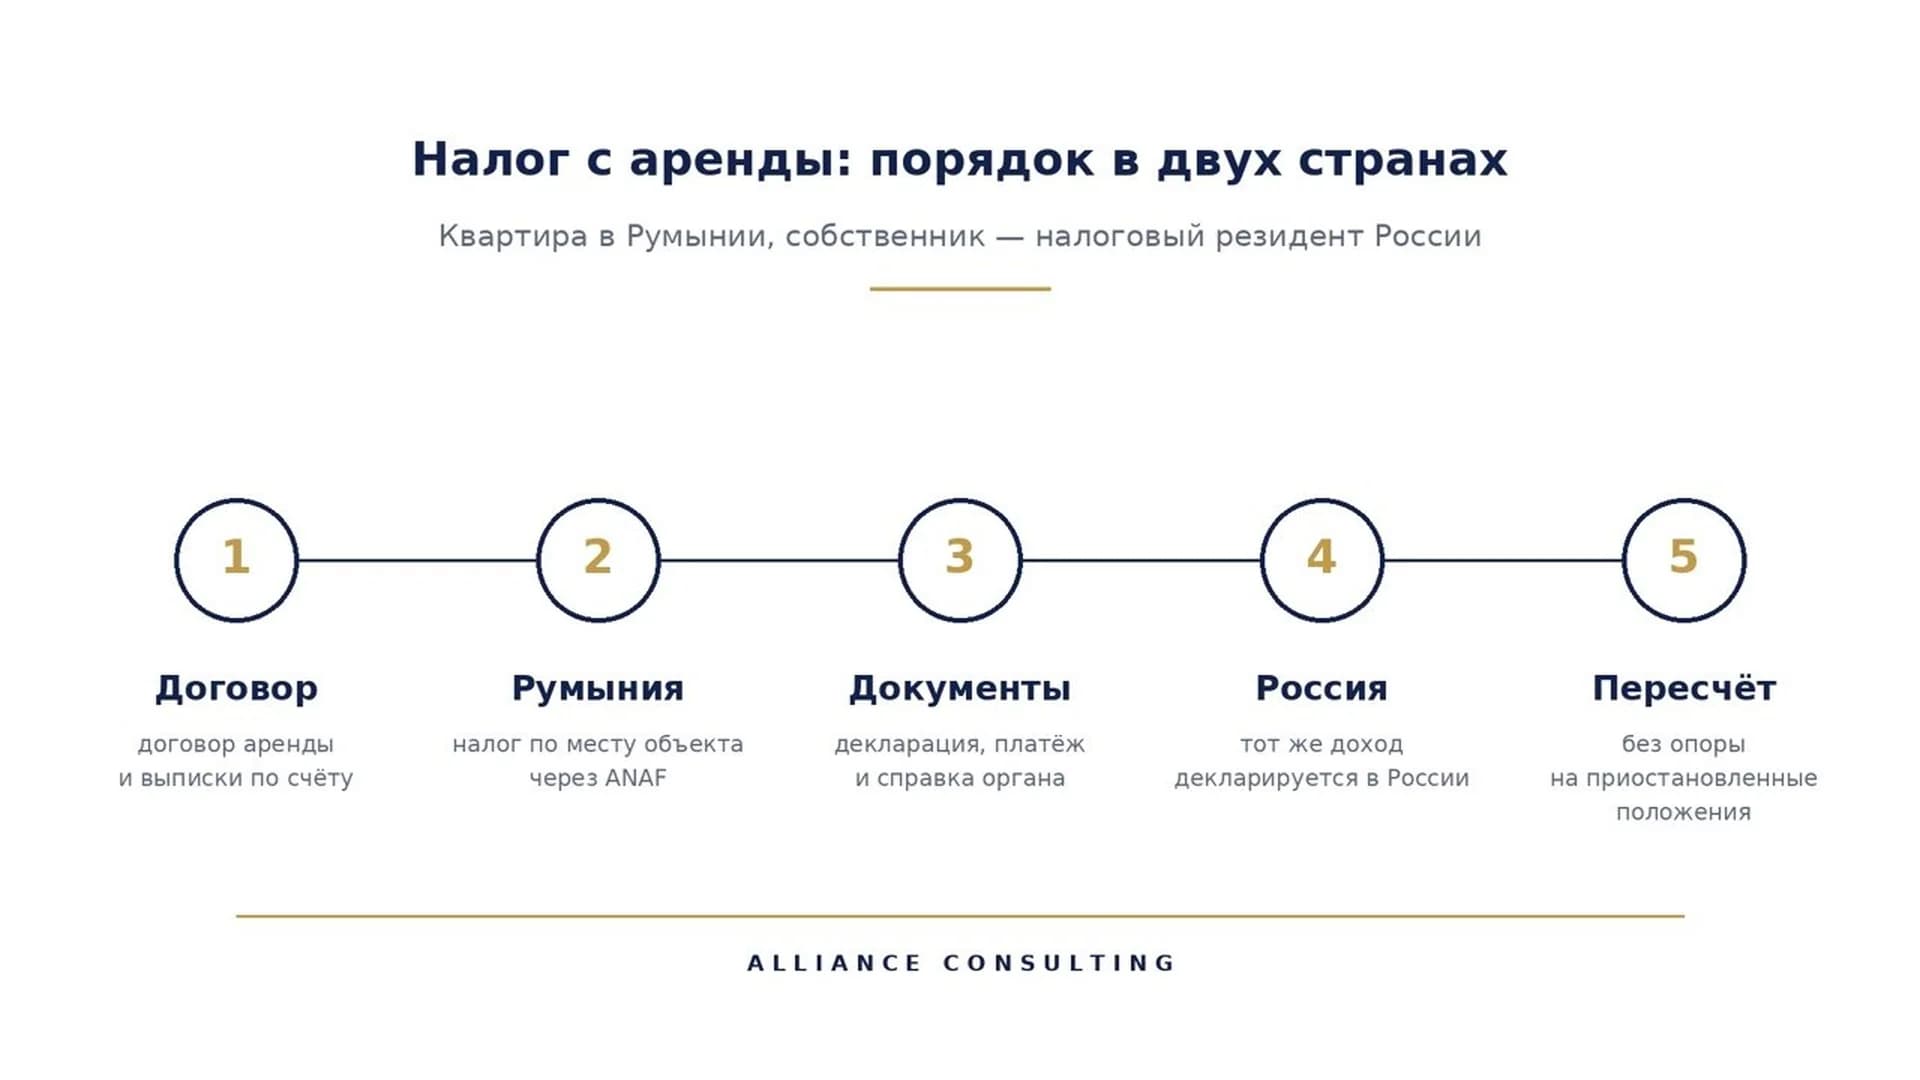
Which documents prove payment of the rental tax?
Three kinds of documents: the return, the payment and a certificate from the authority. For an individual in Romania, these are the single tax return, proof of payment and an ANAF certificate confirming no outstanding debt; for a company — its returns, payment orders, the resolution on the distribution of dividends and confirmation of the tax withheld.
The single tax return is the form an individual uses to report the year's rental income to ANAF; it is filed by the deadline set by the code as of the relevant date.
The ANAF certificate of taxes paid is the document the tax authority of the other country accepts as proof of payment.
The tax residence certificate confirms which country the person is a resident of and is needed by the other side for the calculation.
The lease agreement and bank statements are the basis against which the amounts in all the documents are reconciled.
The documents on the Russian side — the notice of a foreign account, the tax return — are determined by the Tax Code of the Russian Federation and by a Russian specialist; Alliance Consulting does not prepare them and does not advise on them.
Calculated the tax under the suspended agreement — what now?
Recalculate from scratch, without relying on the suspended provisions, and complete the recalculation before the transaction, not after the first return. A calculation under Articles 5–23 and 25 of the 1993 Convention does not apply to income from August 8, 2023, and an error in it surfaces during an audit in either of the two countries.
The sequence: a consultation with a tax specialist covering both jurisdictions — Romania and Russia — with a calculation under the national codes; then the choice of ownership format, individual or company; then the transaction. Alliance Consulting handles the Romanian side — registration of the income, ANAF, payment documents, the company if one is needed; the company does not advise on the Russian side and promises no result there.
What does not work: calculating from memory of the former terms, putting off the recalculation until the property is sold, and counting on one of the sides "not seeing" the income. The exchange of information between tax authorities is a separate provision, and the suspension does not affect it.
How does Alliance Consulting handle the tax side of renting?
As a procedure with a named law and a named authority: Romania's Tax Code, Law 227/2015; the authority is ANAF. The company works under a contract that sets out the timelines, the amount and the working procedure; the contract is concluded only with an individual. Offices in Constanța and Mamaia, licenses publicly available on the website.
A compliance assessment with a written opinion is a free review of your situation before any decisions: which format to own in, which payment documents will be needed, and which parts of the Romanian side the company closes and which remain with a Russian specialist. The first section of the opinion covers whether the status is attainable. The result is a route built out with the sequence, timelines and budget, or a reasoned refusal explaining why.
The working order is strict: status first, then money, then the asset. Personal sanctions are an absolute boundary. And a straight answer: whether this structure suits you. The assessment is free, commits you to nothing and may end in a reasoned refusal explaining why.
Do I have to pay rental tax in Romania if I am a Russian tax resident?
Yes, rental tax has to be paid in Romania: income from real estate is taxed where the property is located under Romania's Tax Code, Law 227/2015, regardless of the owner's residence. The same income is declared in Russia under the Tax Code of the Russian Federation. How the two obligations relate is determined by the national codes, since the main articles of the agreement are suspended.
Is the double taxation avoidance agreement between Russia and Romania in force now?
The agreement between Russia and Romania is partly in force: Articles 5–23 and 25 of the Convention of September 27, 1993 have been suspended since August 8, 2023 by Decree No. 585 and Law No. 598-FZ. The general provisions, including the exchange of information, remain in force. The status on the Romanian side is checked with ANAF as of the relevant date.
Which is better — renting out the apartment as an individual or through a Romanian company?
Renting out the apartment as an individual is simpler with a single property: the single tax return, the payment, an ANAF certificate. Through a Romanian company — with several properties and management through a management company; SRL registration takes about a month and costs €1,300 on confirmed terms as of September 1, 2026. Rates are not given: the choice is calculated during the assessment.
Sources
Romania's Tax Code — Law 227/2015, legislation portal legislatie.just.ro — Monitorul Oficial No. 688 of September 10, 2015, in force since January 1, 2016.
ANAF — Romania's National Agency for Fiscal Administration, official website — administers the tax on rental income, issues certificates of payment and residence certificates.
Decree of the President of the Russian Federation No. 585 "On the suspension by the Russian Federation of certain provisions of international treaties on taxation" — of August 8, 2023, published on the official internet portal of legal information on August 8, 2023.
Federal Law No. 598-FZ on the suspension of certain provisions of international treaties on taxation — official internet portal of legal information — of December 19, 2023.
Alliance Consulting — service page "SRL registration" — company registration, bank account and accounting in Romania.
Author: Sergey Valentinovich Kononov, head of Alliance Consulting. Published: 28.09.2026. Updated: 28.09.2026.
Verified as of 23.09.2026. The legal points, amounts and timelines are current as of this date; the page is updated when they change.